The Floor Gives Way: Bitcoin Breaks $80,000 and the Map Opens Lower
The seventh test was one too many.
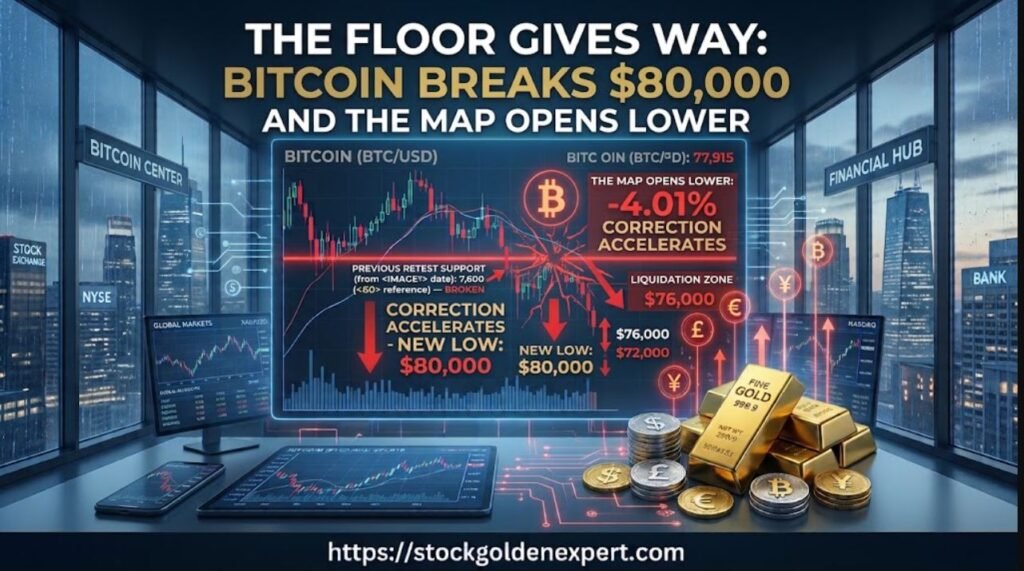
Bitcoin broke decisively below $80,000 on Thursday, falling to a low of $77,737 before settling at $77,775 — the first daily close below the level since before the October range began. The floor that had been defended seven times over five weeks, that had anchored every bullish structure since early October, and that this column had flagged all week as the market’s single most important line, is gone. The range didn’t just tilt this time. It broke.
How the floor finally failed
Breakdowns of well-defended levels rarely happen on the first attempt or the second — they happen when the defenses have been spent. That was precisely the setup here. The failed breakout above $84,800 last week consumed the bulls’ best ammunition: the momentum buyers who chased the ceiling are now trapped and liquidating, the range traders who bought each dip are underwater, and the spot accumulators who defended $80,000 seven times have finally met a seller they couldn’t absorb. Thursday’s move came on $40.9 billion of volume — the third-heaviest session of the year — and it came with the dollar resurgent and risk appetite deteriorating across every market. The floor didn’t fail because of one factor; it failed because every factor aligned at once against a level that had no margin left.
The technical consequence is mathematical. The range that just broke was $80,000 to $84,800 — $4,800 tall — and breakouts from ranges travel the range’s height. Projected from the breakdown point, that target sits near $75,200. Below that, the chart offers the July pivot zone around $73,500 and then the June low near $72,400. None of these are predictions; they are the destinations the structure now points toward if the breakdown follows through.
What the bulls can still argue
Honesty requires the counter-case. First, the breakdown day closed at $77,775 — well off the lows, suggesting the selling met real absorption beneath the broken level rather than free-fall. Second, the leverage purge that made prior declines so violent has largely already happened; open interest remains far below the May peak, and funding rates are neutral to negative, which is where bottoms historically begin, not continue. Third, the structural flows — ETF demand, long-term holder accumulation, corporate treasuries — have not reversed, and those buyers historically appear lower, not at breakdown points.
But the bull case has changed category. It is no longer a “hold the range” story; it is a “find the bottom” story, and those are harder, slower, and far less forgiving of early entries. The buyers of the last five weeks who defended $80,000 are now the overhead supply at $80,000 — everyone who bought the seven tests wants their money back on any rally back to the broken floor. That dynamic is why broken supports become ceilings, and why the first rallies after a breakdown should be sold rather than married.
The playbook from $77,700
For traders, the map is now clean in the way breakdown maps always are: rallies into $79,500–$80,000 are for selling with stops above $80,500; the measured target near $75,200 is the downside objective; and $77,400 is the immediate support that must break to unlock it. For longer-term holders, the only discipline that matters is the one nobody enjoys: don’t add to a falling market out of loyalty to a level that no longer exists. The floor is broken. The market is now negotiating a new one, and those negotiations take weeks, not days. The range is dead. Long live the range below.
Disclaimer: This is market commentary, not investment advice. Trading FX, commodities, equities and crypto carries substantial risk of loss. Past performance is not indicative of future results.
Leave a Reply