The Retest: S&P 500 Holds 7,612 and Finds Its Buyers Again
Every correction lives or dies at its retest. On Friday, the October correction faced its retest — and survived.
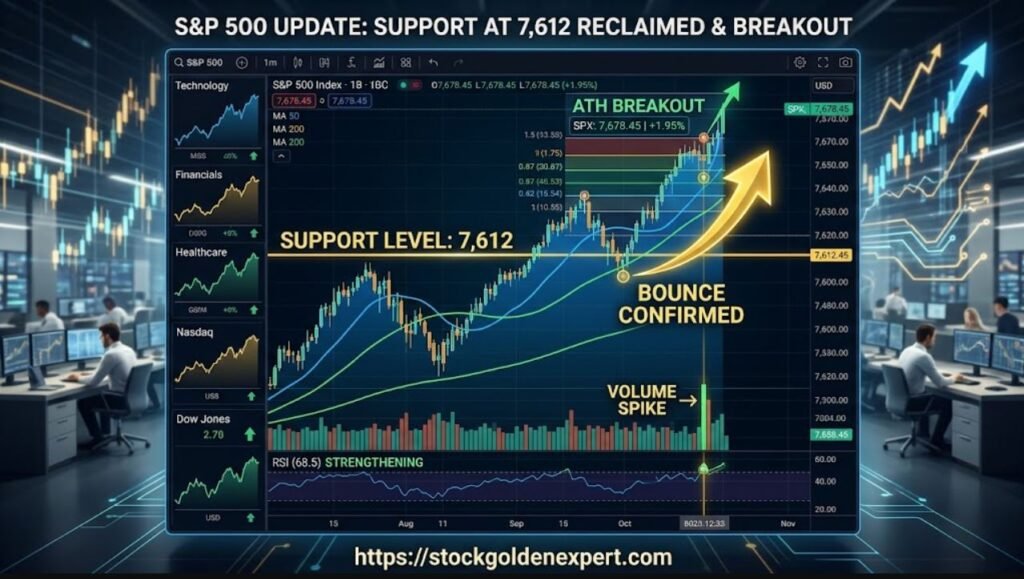
The S&P 500 fell to 7,612 intraday on Friday, within 47 points of the correction low at 7,659… no — within a whisker of breaking it entirely. Then, almost on schedule, the buyers arrived. The index recovered to close at 7,624, down just 0.5% on a session that at its worst looked like it might break the month’s entire structure. The low held. The correction, for the third time this month, found its floor exactly where the map said it should.
Why Friday’s low matters so much
Go back to the framework this column has used all month: the October decline was a correction, not a trend change, provided three conditions held — credit staying calm, the dollar stabilizing, and the index holding 7,600. Friday tested the third condition directly, and the market passed. The bounce off 7,612 came on expanding afternoon volume, led by the same growth leadership that has driven every recovery this year, and finished with the index closing well off its lows. Retests that hold with those characteristics are, historically, the retests that end corrections.
The other two conditions have held all along, and Friday added evidence to both. Credit spreads — the market’s smoke detector — tightened again on Friday, with high-yield spreads now below where they were when the index made its October record. And while the dollar has been firming this week, it has done so gently, against only the euro, leaving the yen-pair-driven earnings pressure that started the correction still in retreat. The loop that drove the slide — strong dollar, squeezed earnings, falling stocks — remains broken.
The anatomy of Friday’s fear
To be fair to the sellers, Friday’s session gave them ammunition. The week’s mixed megacap earnings — some beats, some cautious guides — kept the guidance-jitters theme alive. The dollar’s renewed firmness against the euro revived the translation-drag fear. And the calendar did what the calendar does: late October has a documented habit of producing one final flush before the seasonal rally begins, and every desk in the market knows it. Fear of the flush can become the flush itself, and Friday morning traded exactly like that — a slide driven more by the anticipation of selling than by the presence of it.
That’s worth pausing on, because it distinguishes Friday from the sessions that actually broke markets. Real declines are driven by forced liquidation — margin calls, redemption pressure, credit events. Friday showed none of the signatures: no credit stress, no volatility spike in the bond market, no disorderly breadth. What it showed was skittish profit-taking in front of a weekend, by a market that had recovered 60% of its decline in three sessions and was looking for an excuse to consolidate. The excuse arrived; the excuse was used; the structure survived.
Where the correction stands now
The scorecard after Friday: the index has made two successful defenses of the 7,600–7,620 zone, separated by a 4% round trip. Volatility has fallen back to pre-correction levels. Breadth has repaired. And the calendar now turns genuinely friendly — the historically strongest two-month stretch for equities begins next week, with seasonality, positioning (reduced after the October shakeout), and the earnings calendar all aligning in the bulls’ favor for the first time since the summer.
The risks remain the honest ones: a hot inflation print could revive the dollar and reopen the earnings wound; a guidance disaster from one of the remaining megacap reporters could do damage no seasonality can repair; and a third defense of 7,600, if it comes, would arrive with less ammunition than the first two. But at this point, the burden of proof has shifted decisively. The bears had their week, their retest, and their flush. They broke nothing.
Levels into the new week: 7,612 the line that must hold; 7,700 the first gate; 7,757 the recent recovery high; and 7,844 the record that would confirm the correction as a footnote. The market that made bears look smart for four sessions in October has now made them look premature for two weeks. The year’s final chapter is about to begin, and the index enters it with its structure intact, its credit calm, and its floor defended three times. That is not a bear market’s profile. It never was.
Disclaimer: This is market commentary, not investment advice. Trading FX, commodities, equities and crypto carries substantial risk of loss. Past performance is not indicative of future results.
Leave a Reply