S&P 500 at 7,659: Three Levels That Will Decide This Correction
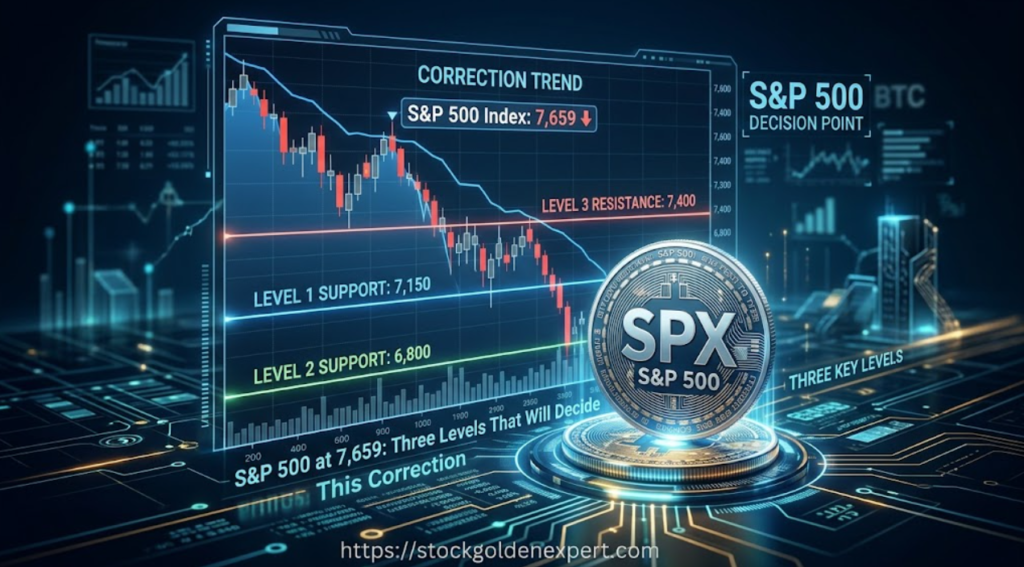
The S&P 500 opens the week at a crossroads, and the map is simpler than the headlines suggest.
The index closed Friday at 7,659, down 2.4% from the October 6 record of 7,844, with the damage concentrated in two high-volume sessions on Wednesday and Thursday. Friday’s volume of 5.5 billion shares was the heaviest of the pullback — a detail that matters, because it means the decline has sponsorship. This isn’t thin-air selling; institutions are repositioning, and their footprints show up in volume.
What the sellers are actually selling
The internal evidence points to a specific thesis being unwound: the strong-dollar earnings story. The decline has been led almost exclusively by multinationals with heavy international revenue, while domestically-focused sectors — utilities, small caps, regional banks — have held up far better. When a correction is driven by one identifiable factor rather than broad economic fear, it tends to resolve when that factor resolves. In this case, the factor is showing early signs of resolution: the dollar just posted its worst week since August.
Credit markets agree with the benign reading. Investment-grade spreads are within a whisker of their cycle tights, and high-yield spreads — the traditional early-warning system for equity declines — haven’t budged. Every genuine equity bear market of the past three decades began with credit stress. There is none today.
The three levels
First, 7,600. Friday’s low was 7,632, and Monday’s early trade held above it. A close below 7,600 would open the August consolidation zone at 7,508, and below that, the line that separates a correction from something more serious: 7,314. That level marks the summer’s pivot point, and losing it would force the market to reprice the entire year’s advance.
Second, 7,700. The index’s first real resistance, where Wednesday’s bounce died. Reclaiming it on a closing basis would signal that the sellers’ urgency is fading — the first step in any bottoming process.
Third, 7,844 — the record. Obviously distant, but worth naming, because the character of this bull market has been record-to-record with corrections in between. If 7,600 holds and this week’s heavy earnings calendar delivers even neutral guidance, a recovery path back to the highs within a month is entirely consistent with how the last three corrections in this cycle resolved.
The week that decides
This is the densest earnings week of the season, featuring the megacap names that drive the index. Their guidance on the dollar and on consumer demand will either validate the correction (dollar-driven misses) or end it (resilient guidance). Either way, the market should have its answer by Friday’s close.
Until the levels speak, the playbook is the correction playbook that’s worked all year: respect the support at 7,600, treat rallies below 7,700 with suspicion, and don’t confuse a two-week, 2.4% pullback with the end of a bull market that has survived three previous tests. Corrections feel like crashes in real time. They almost never are.
Disclaimer: This is market commentary, not investment advice. Trading FX, commodities, equities and crypto carries substantial risk of loss.
Leave a Reply