Sterling Smashes Through 1.34: The Pound’s Quiet Revolution Continues
Some market moves announce themselves with fireworks. Others accumulate so steadily that one day you look up and realize the whole landscape has changed. Sterling’s autumn belongs to the second category — and on Tuesday, it crossed a line that makes the move impossible to ignore.
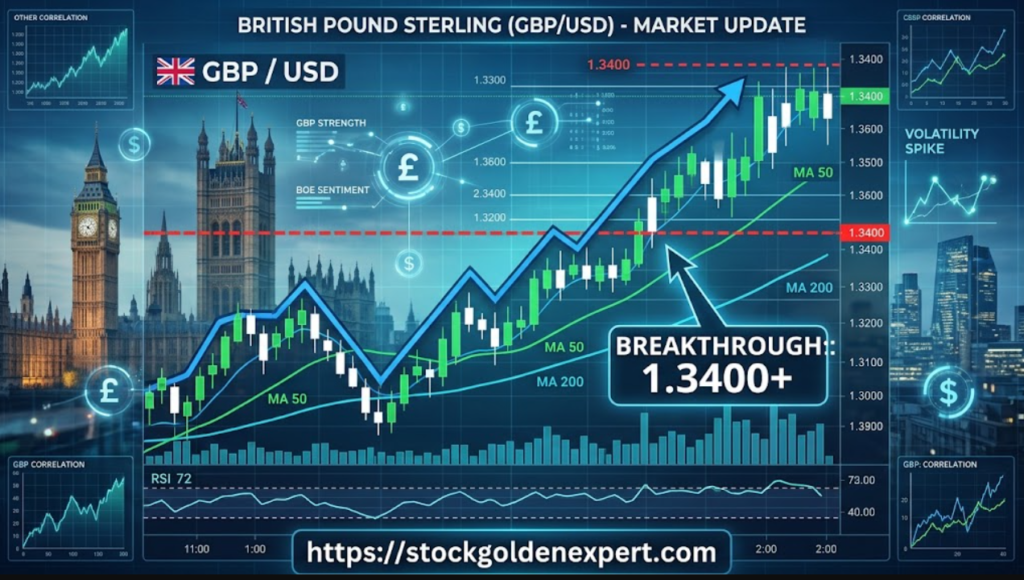
GBP/USD pushed to 1.3408 on Tuesday, its highest level since mid-August, before settling at 1.3391 — the third consecutive session above 1.33 and the sixth daily gain in the last seven. From the early-October panic low of 1.3139, the pound has now rallied 270 pips against the US dollar. Against the euro, the story is even more emphatic: EUR/GBP has fallen to 0.8390, its lowest level since the spring, completing a decline of more than two cents since September.
How an unloved currency became the market’s favorite
Rewind twelve months and sterling was nobody’s idea of a compelling trade. The UK economy was growing at half the pace of America’s, political noise was constant, and the pound carried the baggage of the 2022 crisis that nearly broke the gilt market. The consensus trade was to own dollars and ignore sterling entirely.
What changed was not a dramatic UK recovery — GDP growth remains modest by any standard — but a relative shift. The Bank of England, having front-loaded its inflation fight in 2024 and 2025, arrived at 2026 with the highest policy rate in the G10 and the credibility to keep it there. UK inflation, after falling steadily for two years, stopped falling around the 3% mark and refused to go lower. Wage growth stayed sticky. Services inflation proved stubborn. The data never delivered the clean signal for cuts that the optimists kept forecasting.
Meanwhile, the rest of the world converged in the opposite direction. The ECB spent the year edging toward easing as eurozone growth flatlined. The Fed, expected to cut aggressively in early 2026, cut once and then stopped. The Bank of Japan moved at a glacial pace. In a world where almost every central bank is either easing or paralyzed, the institution that simply holds its ground owns the highest yield — and FX is, at its core, a yield-seeking machine.
The flow evidence backs the story
Positioning data tells us this isn’t just a rate-model story. Speculative accounts have been net long sterling since September, but the real flow has come from real-money investors — pension funds and asset managers reallocating toward UK assets as the rate differential widened in Britain’s favor. Corporate flow adds another layer: UK exporters, burned by the weak pound of 2024, have spent 2026 hedging their dollar receivables at progressively better levels, and each rally has drawn fresh hedging demand that paradoxically supports the currency.
The options market confirms the conviction. Risk reversals in GBP/USD — the market’s expression of which direction it fears more — have shifted decisively in sterling’s favor for the first time since 2021. Dealers report sustained demand for upside structures targeting 1.40, a level that would have drawn laughter at the start of the year.
The technical map from here
1.3408 is the new line that matters. Tuesday’s high sits just below the August peak zone at 1.3440–1.3450, the last meaningful supply before the year’s high of 1.3675. A weekly close above 1.3450 would complete a textbook breakout from the three-month range and open the path to 1.3550 within weeks.
The risk case deserves honest treatment. Sterling’s rally has been a one-factor trade — relative rates — and one-factor trades die when the factor reverses. If UK inflation cracks in the November data and the BoE’s guidance softens, the pound has a long way to fall back toward 1.30. The positioning, while not extreme, is no longer contrarian-friendly. And the broad market backdrop — an equity correction, dollar volatility, quarter-end flows — is an environment where even strong stories get shaken.
But for now, the tape is the tape. Above 1.3450, the pound enters price territory where the chart is clean all the way to the year’s high. Below, the breakout zone at 1.3330–1.3300 provides the first meaningful support, with the line in the sand at 1.3200. Sterling has spent two years being underestimated by everyone, including this column at times. The market’s reappraisal is underway, and reappraisals in FX rarely stop at the first round number they cross.
Disclaimer: This is market commentary, not investment advice. Trading FX, commodities, equities and crypto carries substantial risk of loss. Past performance is not indicative of future results.
Leave a Reply